Small businesses are at the heart of Nigeria’s economy. From roadside traders and market sellers to online vendors, artisans, restaurants, transport operators, and professional service providers, millions of Nigerians depend on small businesses for their livelihoods.
Yet running a small business can be challenging. Entrepreneurs often face limited access to finance, poor record keeping, cash-flow problems, difficulty reaching customers, and the rising cost of doing business.
Digital financial services are helping to address some of these challenges by making payments, financial records, savings, and other business services more accessible.
The Rise of Digital Finance
Digital finance refers to financial services delivered through digital channels such as mobile phones, applications, websites, electronic payment systems, and digital banking platforms.
For small businesses, this can mean receiving payments electronically, transferring money to suppliers, monitoring transactions, and managing business finances without relying entirely on cash.
The growth of digital payments has also changed customer expectations. Many customers now expect businesses to offer convenient payment options.
Digital Payments Make Transactions Easier
A customer may not always have cash available, but they may have access to a bank account or mobile payment service.
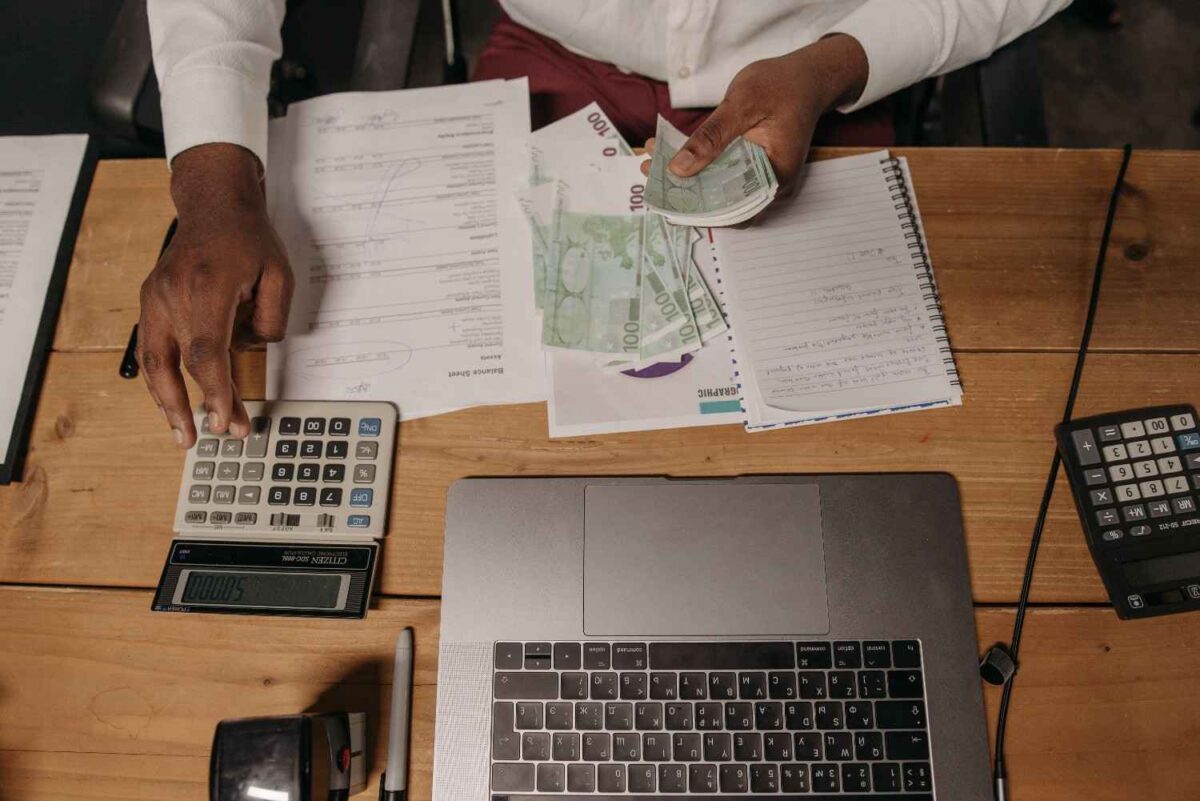
Digital payment options allow businesses to receive money electronically and provide customers with a convenient way to pay.
For business owners, electronic transactions also create records that can help them understand how much money is moving through the business.
Better Records Can Improve Business Decisions
One common challenge among small businesses is the separation of personal and business money.
Without proper records, an entrepreneur may struggle to determine whether the business is actually profitable.
Digital financial tools can help business owners monitor:
- Daily sales
- Business expenses
- Supplier payments
- Customer payments
- Cash flow
- Outstanding transactions
- Monthly revenue
These records can provide a clearer picture of the business.
Digital Tools Can Support Access to Finance
Financial institutions need information when evaluating businesses for certain forms of financing.
A small business with organised transaction records may be better positioned to demonstrate its financial activity than a business that keeps no records.
Digital records do not guarantee access to credit, but they can provide useful information that may support responsible financial assessment.
Entrepreneurs should still carefully evaluate loan terms, interest costs, repayment schedules, and other conditions before borrowing.
Reaching Customers Online
Digital finance works alongside digital marketing.
A small business can use social media, messaging platforms, online marketplaces, and websites to reach customers beyond its immediate neighbourhood.
For example, a local fashion business can display products online, communicate with customers, receive digital payments, and arrange delivery.
Technology can therefore connect the entire customer journey:
Discovery → Communication → Order → Payment → Delivery
Digital Savings and Financial Planning
Digital financial services can also make saving easier for some entrepreneurs.
Business owners can use appropriate financial products to separate business funds, plan expenses, and prepare for future investments.
The most important principle is financial discipline.
A digital wallet or bank account cannot automatically make a business profitable. Entrepreneurs still need to budget carefully, control unnecessary expenses, and understand their cash flow.
Supporting Women and Young Entrepreneurs
Digital finance can be particularly useful for entrepreneurs who have historically faced barriers to traditional financial services.
Women, young entrepreneurs, informal traders, and micro-business owners may benefit from easier payment systems and digital financial tools.
However, access must be accompanied by financial education and consumer protection to ensure that new users understand the services they are using.
The Challenge of Digital Fraud
Greater use of digital financial services also creates new risks.
Business owners need to protect their passwords, PINs, authentication codes, and account information.
They should be cautious about suspicious links, fake payment notifications, impersonation, and fraudulent investment or loan offers.
Customers should also verify payments through official transaction records rather than relying solely on screenshots or messages.
Digital convenience must go hand in hand with digital security.
Financial Literacy Still Matters
Technology cannot replace financial knowledge.
Small business owners need to understand basic concepts such as:
- Revenue
- Profit
- Expenses
- Cash flow
- Pricing
- Debt
- Savings
- Working capital
When financial literacy and digital tools are combined, entrepreneurs can make better decisions.
Building a More Inclusive Digital Economy
For digital finance to benefit more Nigerians, several barriers need to be addressed.
These include:
- Limited digital literacy
- Poor connectivity
- Transaction costs
- Limited access to smartphones
- Electricity challenges
- Fear of digital fraud
- Limited awareness of available financial services
Financial institutions, technology companies, government agencies, and community organisations all have roles to play in addressing these challenges.
What Small Businesses Can Do
Entrepreneurs can start with simple steps:
- Separate personal and business finances.
- Keep accurate sales and expense records.
- Offer trusted digital payment options.
- Review transaction records regularly.
- Learn basic financial management.
- Protect account credentials.
- Compare financial products before using them.
- Build an online presence where appropriate.
- Keep evidence of business transactions.
- Reinvest strategically rather than spending all business income.
Conclusion
Digital finance is changing how small businesses operate in Nigeria.
Electronic payments, digital records, online customer engagement, and financial technology can make everyday business activities faster and more organised.
But technology is only a tool. Sustainable business growth still depends on good products, satisfied customers, disciplined financial management, reliable service, and sound decision-making.
When digital tools are combined with financial literacy and responsible entrepreneurship, they can help Nigerian small businesses become more organised, competitive, and prepared for the future.
