How Digital Payment Platforms Are Transforming Financial Transactions in Nigerian Market Communities
Why Digital Payments Matter in Nigerian Market Communities
Nigerian market communities remain the backbone of the country’s informal economy, supporting millions of traders, artisans, farmers, wholesalers, and retailers. Yet despite their enormous economic contribution, many markets still rely heavily on cash transactions, exposing traders to theft, accounting challenges, and limited access to formal financial services. Digital payment platforms are changing this reality by making transactions safer, faster, and more transparent.
Cash management presents significant operational challenges for market traders. Handling large volumes of physical cash—especially on busy market days—increases the risk of theft, human error, and financial loss. Traders also spend valuable time counting money, making change, and reconciling daily sales. Digital payment platforms eliminate many of these challenges by converting transactions into secure electronic records that can be verified instantly while reducing dependence on physical cash.
For market associations, digital payments strengthen financial accountability. Membership dues, market levies, cooperative savings, welfare contributions, and development funds can all be collected electronically, creating accurate transaction records that reduce disputes and improve financial transparency. Communities that embrace digital financial management often experience stronger governance, increased member confidence, and better financial management than those relying entirely on cash.
The Most Practical Digital Payment Platforms for Nigerian Market Traders
Successful digital payment solutions in Nigerian markets are those that remain accessible regardless of the type of mobile phone a trader owns. USSD banking services continue to be among the most inclusive digital payment options because they function on basic mobile phones without requiring internet connectivity or smartphones. By simply dialling short banking codes, traders can transfer money, receive payments, check balances, and complete transactions from virtually anywhere.
Mobile payment platforms such as PalmPay, OPay, Moniepoint, and Kuda have also expanded rapidly within Nigerian markets by offering user-friendly interfaces, competitive transaction costs, and merchant-focused services. Their widespread agent networks make deposits and withdrawals convenient, even in areas with limited banking infrastructure. Many traders now use these platforms for supplier payments, customer transactions, and daily business operations.
Point-of-Sale (POS) terminals have become equally important. Banks and fintech companies provide merchants and POS agents with devices that allow customers to pay using debit cards or bank transfers without requiring specialised equipment from buyers. As Nigeria’s instant payment infrastructure continues to improve, these technologies make digital transactions increasingly practical for everyday market activities.
How Market Associations Can Encourage Digital Payment Adoption
Market associations play a central role in accelerating digital payment adoption across Nigerian communities. When association leaders introduce digital payment methods for membership dues, market levies, welfare contributions, and savings schemes, members naturally become familiar with digital financial tools through regular use. This institutional adoption often becomes the first step toward wider commercial use by individual traders.
Training programmes organised by market associations can significantly reduce the knowledge barriers that discourage many traders from embracing digital finance. Practical demonstrations showing how to open digital wallets, receive transfers, confirm payments, and resolve common transaction issues help build confidence among members. These sessions are especially valuable for traders with limited previous experience using digital financial services.
Peer learning further strengthens adoption. Traders who become comfortable with digital payments often assist neighbouring traders, creating informal support networks that encourage confidence throughout the market. This community-based learning approach allows digital payment knowledge to spread naturally while reducing dependence on external trainers.
Promoting Security and Fraud Awareness
Digital payment adoption must be accompanied by strong security awareness. As more traders move from cash to electronic transactions, fraudsters increasingly target users through phishing calls, fake payment alerts, SIM swap attacks, social engineering, and other forms of financial fraud. Without adequate education, first-time digital payment users can become vulnerable to financial losses.
Basic security practices greatly reduce these risks. Traders should never disclose their PINs, passwords, One-Time Passwords (OTPs), or account verification codes to anyone. Payments should always be verified through official banking applications, USSD confirmations, or account balance notifications before goods are released to customers. Suspicious calls claiming to represent banks or payment companies should be treated with caution and verified independently through official customer service channels.
Market associations can reinforce these practices by making digital payment security a regular part of meetings, workshops, and community announcements. Continuous awareness helps traders recognise emerging fraud techniques and creates a culture of collective vigilance that strengthens financial safety across the entire market.
The Long-Term Development Impact of Digital Payments
The benefits of digital payment systems extend well beyond convenience. Every electronic transaction automatically creates a financial record that documents business activity over time. These transaction histories provide market traders with formal financial evidence that many banks, microfinance institutions, and lenders require when assessing loan applications or providing other financial services.
For traders, maintaining consistent digital transaction records improves access to business financing, inventory credit, insurance products, and other financial opportunities that support enterprise growth. Businesses that were previously invisible to the formal financial sector become increasingly eligible for services that help them expand.
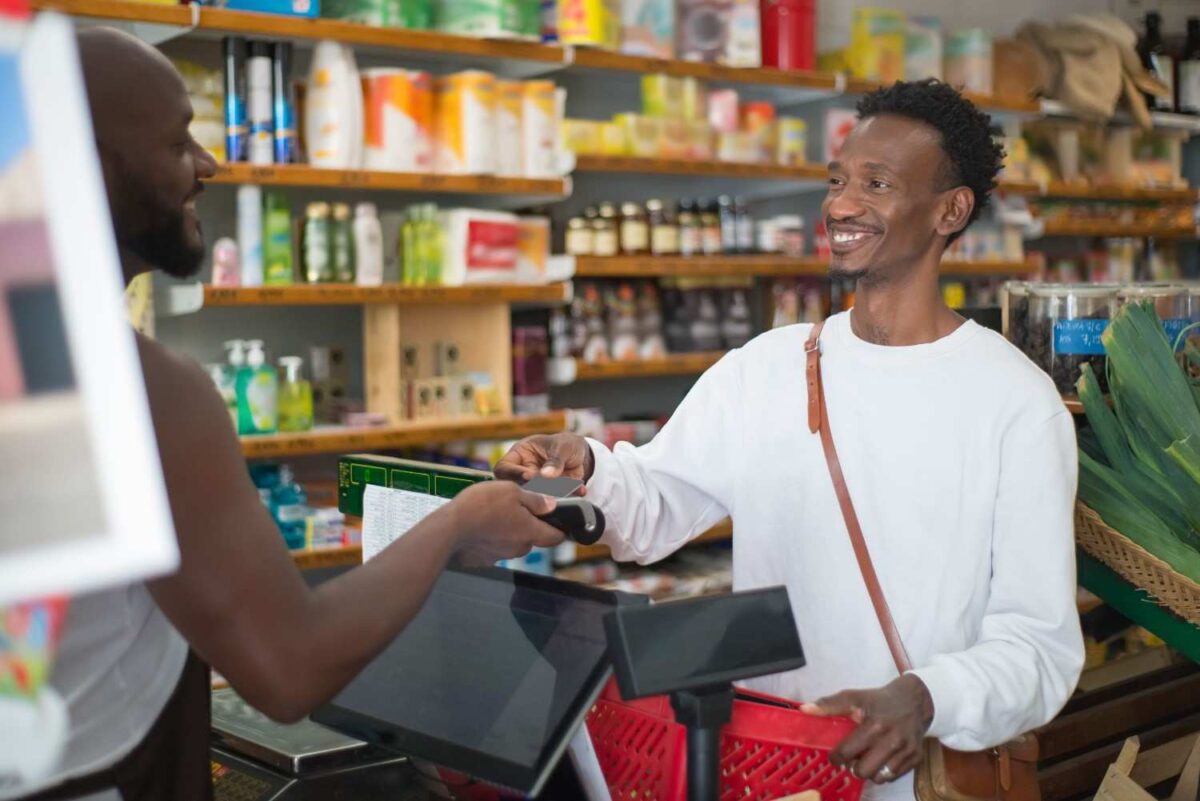
At the community level, digital payment infrastructure contributes to broader economic development. Markets equipped with reliable digital payment systems operate more efficiently, reduce transaction costs, attract customers who prefer cashless payments, and integrate more effectively into Nigeria’s growing digital economy. These improvements enhance the competitiveness of local markets while creating an environment that supports entrepreneurship, investment, financial inclusion, and sustainable economic growth.
Digital payment platforms are therefore more than technological innovations—they are essential tools for modernising Nigerian market communities. By combining accessible payment technologies, practical training, strong security awareness, and supportive market leadership, Nigerian markets can build safer, more transparent, and more inclusive financial ecosystems that benefit traders, consumers, and the wider economy alike.
